Learning center
First Time Buyer
Buying a home with lots of questions? You're at the right place. Articles to help you understand how it all fits together and what to expect.
Overview
Most first-time buyers are surprised twice: once by how little down payment they actually need, and second by how much the small details — earnest money, inspection timelines, insurance quotes in fire-rated areas and buyer transaction & loan related closing costs control the outcome. These guides explain the whole process in plain english so you know what to expect.
Who this is for: First time home buyers and those needing a refresher
What you'll learn
- •Down payment & buyer's closing costs - understand the funds required
- •Loan qualifying & underwriting - what documents are needed and the process
- •Understand loan appraisal and property inspections
28 guides in this topic
 Agent Loan Tips
Lenders, mortgage brokers and loan officers, what's the difference?
Who you choose for your home loan matters -- lenders, mortgage brokers and even loan officers are not the same
Read the guide → Agent Loan Tips
How to spot a bad pre-approval letter
A bad mortgage pre-approval letter can cost a buyer their dream home and a real estate agent weeks of wasted time. Not all pre-approval letters are created equal. Some are based on little more than a quick online questionnaire, while others involve a detailed review of the buyer's financial situation by an experienced loan officer. Knowing the difference can help agents avoid financing surprises, underwriting problems, delayed closings, and canceled transactions.
Read the guide → First Time Buyer
What Documents Are Needed For a Mortgage
Requirements by Loan Type. The paperwork required depends on your loan program, how you earn your income, and your financial situation. Conventional, FHA, VA, and USDA loans share many of the same requirements, but there are some important differences.
Read the guide → Monthly Payment Tips
Impound account tips
Depending on where you live and who you’re talking to, you may also hear these accounts called escrow accounts, impounds or trust accounts. Different names, but essentially the same concept: part of your monthly mortgage payment is set aside so your mortgage servicer can pay certain property-related bills when they come due.
Read the guide → First Time Buyer
First Time Home Buyer Basic Tips
Buying your first home can feel complicated, but working with an experienced Realtor and loan officer can make the process much easier. Understanding a few basic numbers and loan requirements before you start shopping can also help you avoid surprises.
Read the guide → Rate Tips
Shop the Loan Price, Not the Rate — What Does That Mean?
After my nearly 40 years in lending, there is one constant I can attest to. The bigger the lender the higher their loan price! What exactly is the loan price? It's the combination of the rate and lender fee tied to that rate
Read the guide → Loan Program tips
FHA Loan Tips
FHA loans are popular because they offer a low down payment, flexible credit guidelines, and more forgiving qualification requirements than many conventional loans. And despite a common misconception, you do not have to be a first-time home buyer to qualify.
Read the guide → Loan Program tips
USDA Income Limits
USDA home loans can be an excellent option for qualified home buyers because they offer zero down payment financing, competitive rates, and relatively low mortgage insurance costs.
Read the guide → Loan Program tips
Conventional, FHA, VA, USDA Loans — How Do They Compare?
Choosing the right mortgage program can make a major difference in your down payment, monthly payment, qualifying requirements, and overall loan costs. Conventional, FHA, VA, and USDA loans each have different advantages and restrictions.
Read the guide → Property Condition & Appraisal
When an appraisal isn't needed
Fannie Mae’s appraisal waiver program—officially called Value Acceptance—can allow certain homebuyers and homeowners to complete a mortgage without a traditional appraisal.
Read the guide → Property Condition & Appraisal
Condo vs House
Choosing between a condo and a single-family house involves more than comparing purchase prices. Your monthly costs, maintenance responsibilities, HOA rules, privacy, financing, location and long-term plans can all affect which option makes the most sense.
Read the guide → Agent Loan Tips
How Fast Can You Close a Home Loan?
Purchase home loans can close in as little as 14 days or less with the right mortgage broker! Buying a home is exciting, but waiting 30, 45, or even 60 days for your mortgage to close can be frustrating. The good news? You don't have to wait that long when you use an experienced mortgage broker.
Read the guide → Buyer funds explained
Seller Concessions- How It Works
Seller concessions—also called seller credits—can be a powerful way to reduce the amount of cash a homebuyer needs at closing. Depending on the loan program, they may help pay closing costs, prepaid expenses, or even the cost of obtaining a lower mortgage rate.
Read the guide → Loan Program tips
USDA Zero down Home Loan
USDA home loans can be one of the best financing options for qualified homebuyers because they offer 100% financing with no down payment required. They can also provide competitive interest rates, relatively low mortgage insurance costs, and flexible underwriting.
Read the guide → Agent Loan Tips
It's the Loan Officer not the Lender
The ugly truth about getting a home loan? It can be a hassle. There are documents to provide, deadlines to meet, questions to answer, and potential problems that can pop up along the way. But the right loan officer can make the process much easier. The key thing to understand is no matter who the lender is--it's the (MLO) mortgage loan officer -- that makes for a smooth loan process.
Read the guide → Loan Qualifying
DTI, debt to income ratio explained
DTI compares your qualifying monthly debts with your gross qualifying monthly income. While the basic calculation is simple, mortgage guidelines determine exactly which debts and income can be used.
Read the guide → Monthly Payment Tips
Mortgage payment tips
Understanding your true monthly housing payment is critical when buying or refinancing a home. Your mortgage payment is more than just principal and interest. Taxes, insurance, mortgage insurance, HOA dues and other expenses can significantly affect what you actually pay each month.
Read the guide → Buyer funds explained
Closing Costs Tips
Closing costs are more complicated than your down payment. They can include lender fees, title and escrow charges, insurance, prepaid interest, taxes, impound reserves and other expenses. The important thing is knowing what you're paying, which costs can vary, and where you may be able to save money.
Read the guide → Monthly Payment Tips
PITI and what it means -mortgage payment explained
Your mortgage payment may include more than just principal and interest. Understanding the full monthly housing expense—including property taxes, homeowners insurance, mortgage insurance and HOA dues when applicable—can help you budget accurately and avoid surprises.
Read the guide → Rate Tips
Why is the loan price important?
When shopping for a mortgage, comparing interest rates alone can be misleading. Every mortgage rate comes with a cost—or sometimes a lender credit. Looking at both together gives you a much better way to compare your options.
Read the guide → Rate Tips
Why A Fed Hike or Cut doesn't change Mortgage Rates
A common misconception is that when the Federal Reserve raises or lowers interest rates, mortgage rates automatically move by the same amount. They don't.
Read the guide →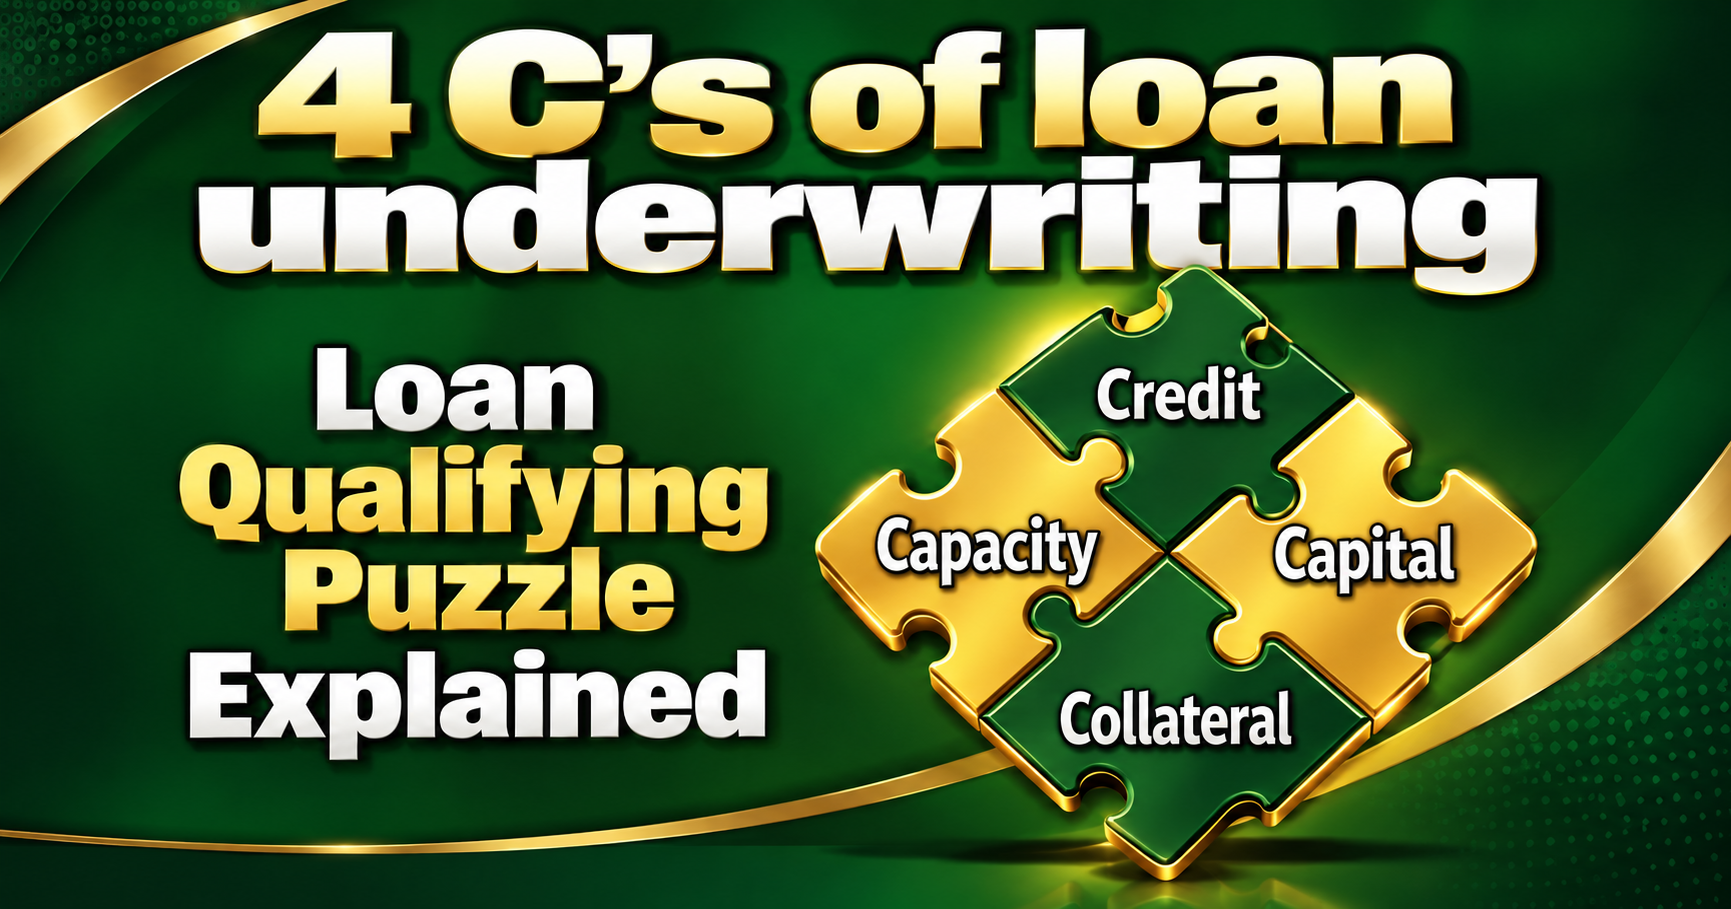 Loan Qualifying
4 C's of Loan Qualifying
Getting a mortgage approved involves much more than having a good credit score and enough money for a down payment. Mortgage underwriters evaluate four major areas when determining whether a borrower and property meet loan guidelines. These are commonly known as the 4 C’s of mortgage underwriting:
Read the guide → Monthly Payment Tips
Property taxes tips California
California Property Taxes Explained — Especially Supplemental Property Taxes which is a county tax assessor's way of adjusting property taxes after a property changes ownership or qualifying new construction is completed.
Read the guide → Rate Tips
Rate Lock Tips to Help You Get the Best Rate
Mortgage rates can change daily—sometimes more than once a day. Understanding when to lock your rate, when you might consider floating, and what actually determines your mortgage rate can help you make a better-informed decision.
Read the guide → Monthly Payment Tips
Seller Funded Buydowns: Everything You Need to Know
A seller-funded temporary rate buydown can lower your mortgage payment during the first few years of homeownership. It can be a valuable tool, but the lower payment is temporary, so it’s important to understand the full cost and long-term payment before deciding whether a buydown makes sense.
Read the guide → Rate Tips
Why Mortgage Brokers Beat banks & big lenders
When shopping for a mortgage, one of the biggest misconceptions is that a big bank or national mortgage company must have the lowest rates because of its size. That is often not the case.
Read the guide → Loan Qualifying
What docs are needed for your home loan?
What Documents Do You Need to Get a Home Loan? Getting a home loan requires paperwork—but there’s a reason behind almost every document your lender requests. Mortgage lenders gener
Read the guide → First Time Buyer
More tips for first time home buyers
First-Time Home Buyer Tips — What You Need to Know Before You Buy Buying your first home is exciting—but there are a lot of moving parts. The good news is that the process becomes
Read the guide →Get a straight answer today
No credit pull to start, no sales pressure, and a real quote you can compare line by line against any bank or big lender.