
Agent Loan Tips
Realtor Tips: Property Improvements & Appraisal Issues
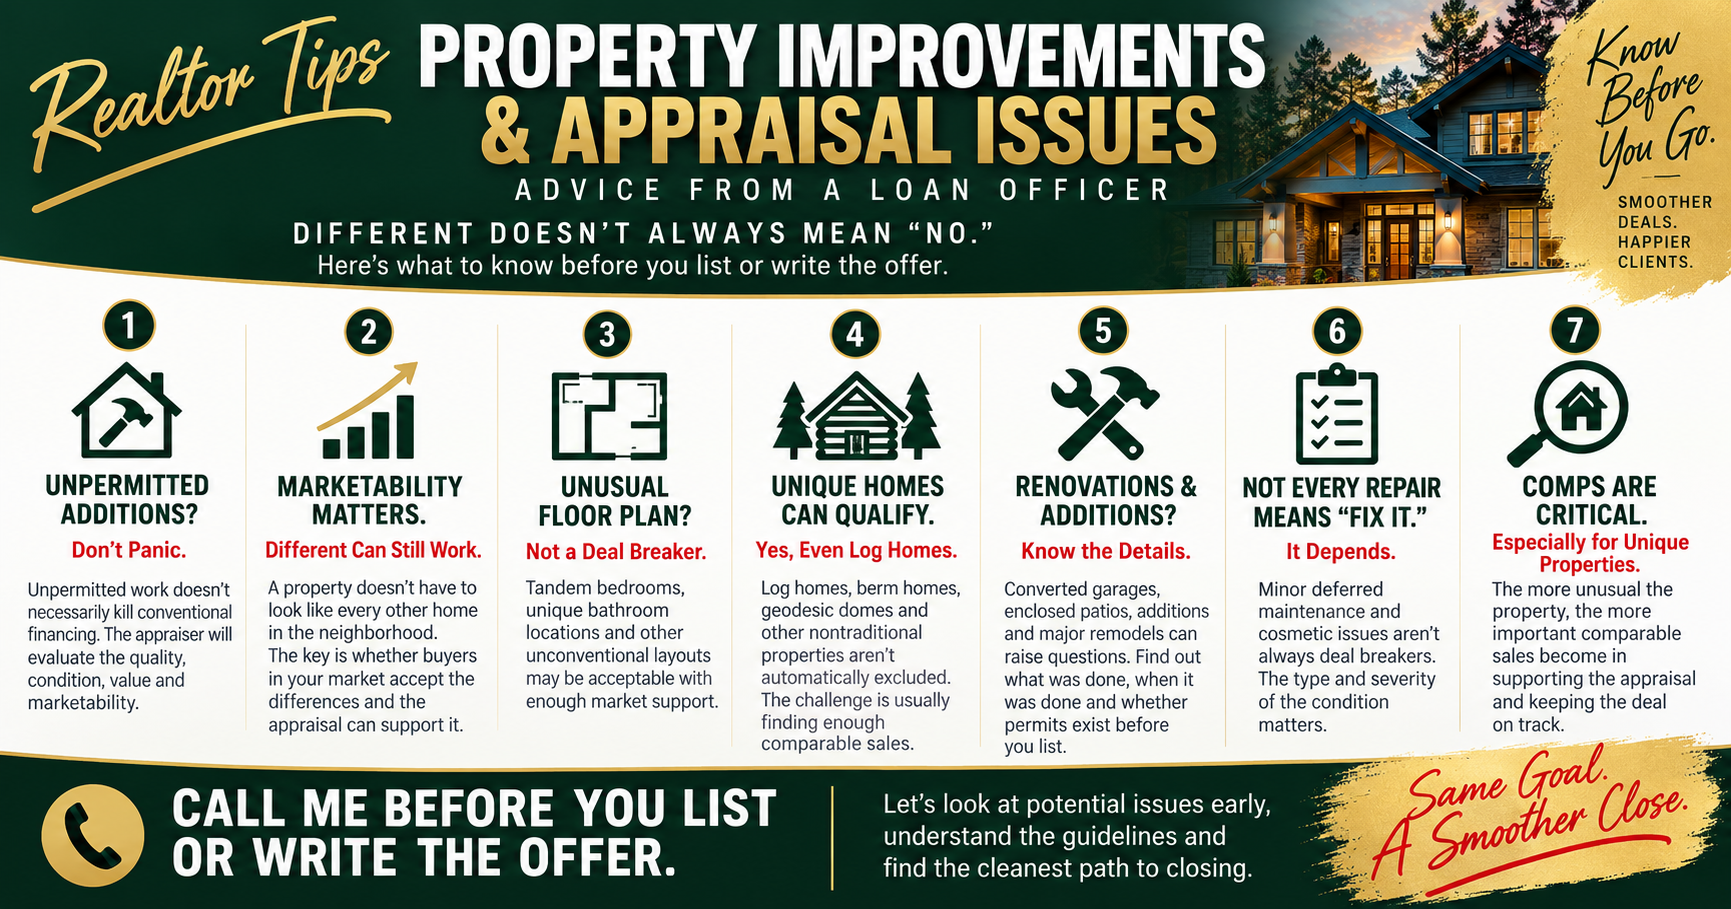
Realtor Tips: Property Improvements & Appraisal Issues
What I Tell Realtors About Property Issues Before an Appraisal
As a loan officer, one of the calls I frequently get from Realtors sounds something like this:
"Dennis, this house has an unpermitted addition. Can we finance it?" Or:
"The garage was converted years ago. Is that going to kill the loan?"
My answer is usually: don't assume there's a problem until we look at the entire situation.
Fannie Mae and Freddie Mac guidelines provide more flexibility with certain property characteristics than many agents and borrowers realize.
What to know
Don’t automatically panic over an unpermitted addition. Unpermitted work does not necessarily kill conventional financing. What the appraiser says about the quality, condition, value and marketability of the improvement can be critical.
Marketability is often the bigger issue. A property can be different from neighboring homes and still potentially qualify. The key question is whether buyers in that market accept the differences and whether the appraisal can support them.
An unusual floor plan isn't automatically a loan killer. Tandem bedrooms, unusual bathroom locations, converted areas and other unconventional layouts may be acceptable when there is sufficient market support.
Unique homes may still be loanable, but don't expect a fast close. Log homes, berm homes, geodesic domes and other unusual properties aren't automatically excluded. The bigger challenge may be finding enough comparable sales to support value and marketability. The more unique the property, the more difficult the process.
Pay attention to renovations and additions before you list. Converted garages, enclosed patios, additions and major remodels can raise appraisal questions. Knowing what was done—and whether permits exist—can save time once you're in escrow.
Not every repair item means the seller has to fix it. Minor deferred maintenance and cosmetic issues aren't necessarily deal breakers. The type and severity of the condition matter.
The more unusual the property, the more important the comps become. If you're listing a unique home, good comparable sales can become extremely important in supporting the appraisal and helping the transaction move forward.
Here are some things I recommend Realtors watch for.
1. Don't automatically panic over an unpermitted addition
If you discover an addition or alteration that apparently wasn't permitted, don't immediately assume conventional financing is impossible.
The appraiser may need to address the quality and appearance of the work and, depending on the circumstances, its effect on value and marketability.
As a Realtor, the best thing you can do is identify the issue early.
Tell your loan officer before the appraisal whenever possible. That gives us an opportunity to look at the situation before it becomes a last-minute surprise.
2. Marketability is often the bigger issue
When I look at an unusual property, one of the questions I'm thinking about is:
Would typical buyers in this market accept this property?
A house doesn't necessarily have to look exactly like every other house in the neighborhood.
An oversized addition, unusual construction, converted area or different design may be acceptable. But if the feature negatively affects marketability or value, the appraiser needs to address it.
For Realtors, local market knowledge can be extremely helpful. If similar properties have sold successfully in the area, those sales may help demonstrate market acceptance.
3. An unusual floor plan isn't automatically a loan killer
I've seen agents become concerned because a house has tandem bedrooms, a strange bathroom location, an unconventional addition or another awkward layout.
That doesn't necessarily mean we can't finance it.
The appraiser will consider how the layout affects functionality, value and marketability. Comparable properties with similar characteristics can be particularly helpful.
So when you're preparing a listing with an unusual layout, start looking for similar sales early.
4. Unique homes can still get conventional financing
Log homes and other nontraditional properties can make Realtors nervous because they're harder to compare with typical homes.
But "unique" doesn't automatically mean "ineligible."
The challenge is often finding enough market data for the appraiser to develop a credible opinion of value and demonstrate that there is a market for the property.
That may require older comparable sales, sales farther away or comparable properties from competing neighborhoods.
If you're listing a unique property, involve the loan officer early rather than waiting until you're already deep into escrow.
5. Pay attention to renovations and additions before you list
When walking a property before listing it, look closely at anything that appears to have been added or substantially changed.
Converted garages, enclosed patios, room additions, remodeled areas and other significant improvements can all create questions during the appraisal.
Ask the seller:
Was it permitted?
Who completed the work?
When was it completed?
Do they have permits, plans, invoices or other documentation?
You may not need every document, but knowing the answers before accepting an offer can prevent unnecessary surprises later.
6. Not every repair item means the seller has to fix it
Another common misconception is that every condition item mentioned by an appraiser automatically has to be repaired.
That's not necessarily the case.
Minor deferred maintenance and cosmetic items can be treated differently from conditions that affect safety, soundness, structural integrity or eligibility.
The specific issue matters.
If an appraisal comes back with a condition you're unsure about, call the loan officer before telling the seller that repairs are required. Let's determine exactly what the lender and loan program require first.
7. The more unusual the property, the more important the comps become
This may be the biggest takeaway for Realtors. If you're listing a property with an unusual feature, start thinking about comparable sales before the appraiser ever arrives.
Look for homes with similar:
- Additions or conversions
- Floor plans
- Construction styles
- Size and functionality
- Condition
- Unique characteristics
The perfect comparable may not exist. But good market evidence can make a significant difference in helping the appraiser analyze the property.
My Advice to Realtors
Don't wait until the appraisal comes back to find out whether a property characteristic could create a financing issue.
If you're looking at a property with an unpermitted addition, converted garage, unusual floor plan, major renovation or unique construction, send it to me before you get too far into the transaction.
I'd much rather look at a potential issue upfront than have everyone scrambling a week before closing.
The goal isn't to find reasons a property can't be financed.
The goal is to identify potential problems early, understand the applicable loan guidelines and find the cleanest path to closing.
- #agent loan tips
- #Property condition
More Agent Loan Tips guides
Disclaimer: Informative opinion based on decades of experience, not legal advice. Guidelines change and lenders differ in their interpretation and overlays — verify details with the lender handling your loan.