
Learning center
Manufactured Home
Understand the special rules that apply to manufactured home loans.
Overview
Financing a manufactured home requires a loan officer with the experience and skill set to get the job done. Unfortunately, many loan officers are unfamiliar with them! It's important to know manufactured homes are treated differently from a site built home and every property has its own distinct challenges including confirming the foundation is acceptable, any modifications/additions either are done with permits or can be certified, overcoming missing HUD tags or Data Plates, how loan type restrictions or lender overlays affect each deal, and making sure there are suitable, like kind comps for the appraisal. Don't trust your manufactured loan to an inept loan officer and expect a successful on time closing!
Who this is for: Manufactured home buyers, owners looking to refi and Agents
What you'll learn
- •How manufactured, modular & mobile homes differ
- •What to do when HUD tags and/or Data Plate are missing
- •Foundation Cert requirements based on loan program
- •Manufactured Home financing red flags
- •How to spot second move homes and how they can kill your loan
5 guides in this topic
 Agent Loan Tips
Manufactured Home Red Flags
Financing a manufactured home can be more complicated than financing a traditional site-built home. Property condition, HUD documentation, foundation requirements, prior moves, land ownership and even the lender you choose can affect whether the home qualifies.
Read the guide → Agent Loan Tips
Manufactured, Modular or Mobile Home — What's the Difference?
Factory-built homes can look very similar, but whether a property is classified as a manufactured, modular, or mobile home can make a major difference when it comes to financing.
Read the guide →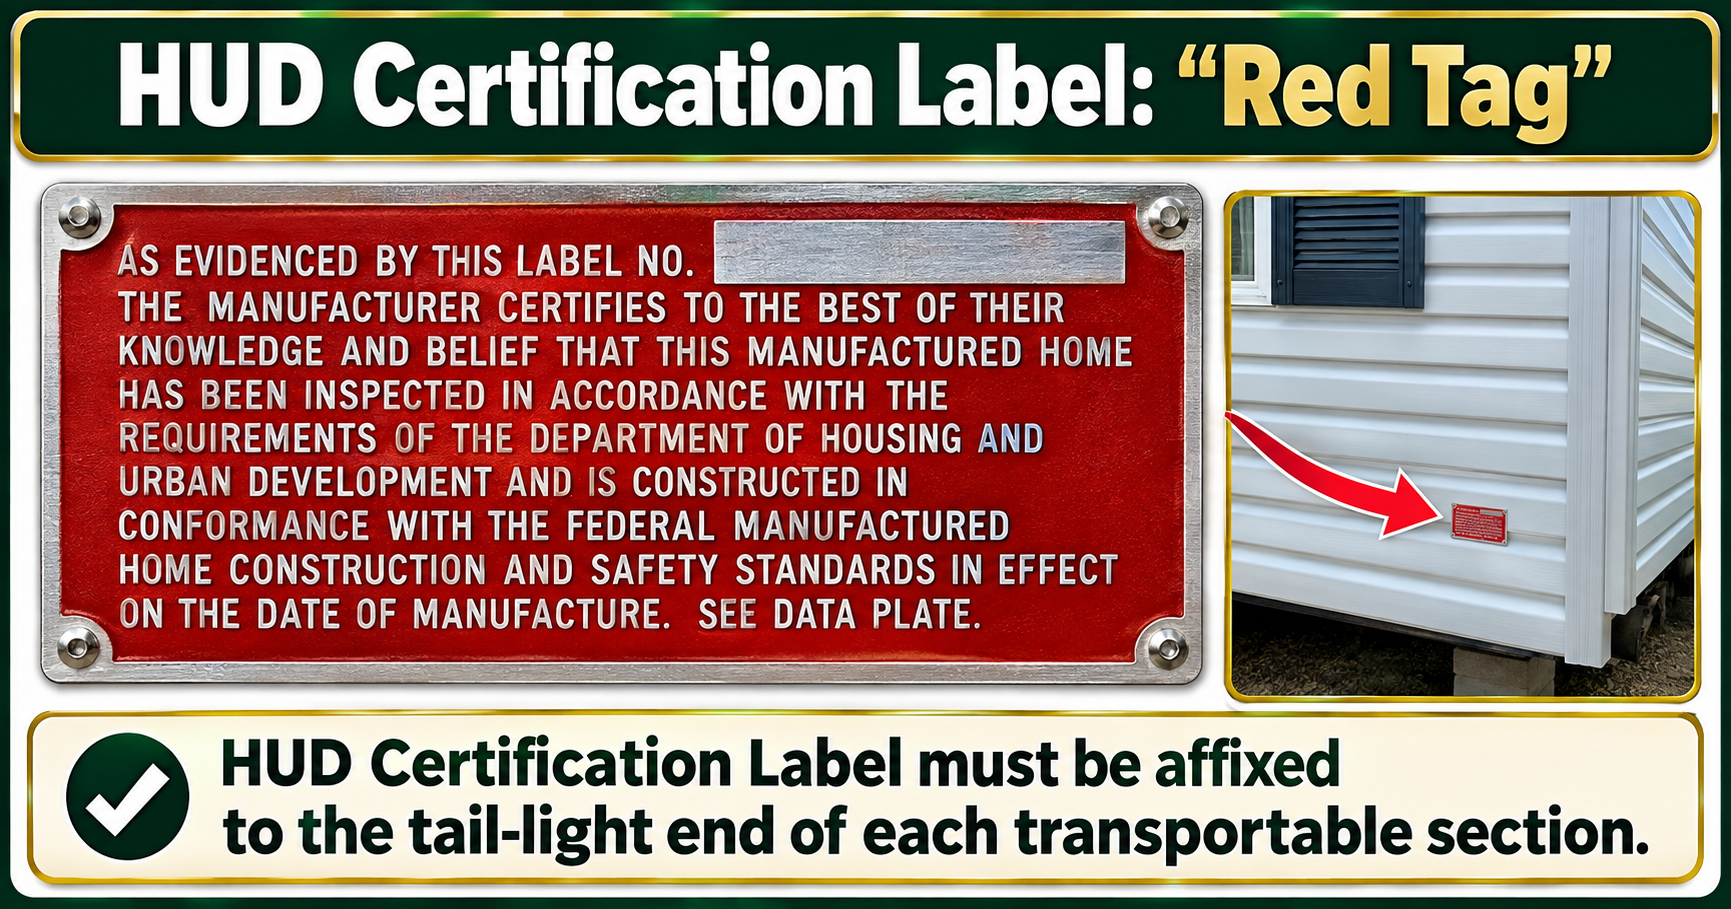 Agent Loan Tips
Manufactured HUD Tags missing?
Buying or refinancing a manufactured home can involve a few extra requirements compared with a traditional site-built home. One common issue is discovering that the HUD certification labels—often called HUD tags or red tags—or the home’s Data Plate are missing.
Read the guide → Manufactured Home
Manufactured Loan Tips
Financing a manufactured home can be more complicated than financing a traditional site-built home. The key is identifying potential property issues early and working with a lender that understands manufactured-home guidelines.
Read the guide → Manufactured Home
USDA Manufactured Loans
USDA loans can be an attractive way to finance a manufactured home, particularly for buyers looking for a zero-down option in an eligible rural area. Manufactured homes, however, have additional property requirements that don't apply to most site-built homes.
Read the guide →Get a straight answer today
No credit pull to start, no sales pressure, and a real quote you can compare line by line against any bank or big lender.