
Refinancing Tips
A 1% Rate Drop Can Cut Your Principal & Interest Payment About 10%
Mortgage Refinance Rule of Thumb: A 1% Rate Drop Can Cut Your Principal & Interest Payment About 10%
When mortgage rates fall, homeowners often ask the same question:
“How much lower does my rate need to go before refinancing makes sense?”
There is no single answer that works for everyone, but there is a simple rule of thumb that can help you quickly estimate the potential savings:
What to know
- A 1% reduction in your mortgage rate can often reduce your monthly principal and interest payment by roughly 10%.
- A 0.50% rate reduction may still produce meaningful savings, especially with a larger loan balance.
- Your actual savings depend on your loan balance, remaining term, new loan term, and interest rates.
- Don't look at the rate alone. Compare the monthly savings with the cost of refinancing.
- Calculate your break-even point to determine how long it may take to recover the refinance costs.
- A refinance can sometimes make sense even without a full 1% rate reduction.
- The best way to know is to run the actual numbers for your mortgage.
1. The 1% Mortgage Refinance Rule of Thumb
As a quick estimate, every 1 percentage point reduction in your mortgage rate can reduce your monthly principal and interest payment by approximately 10% on many standard 30-year mortgage scenarios.
For example, if your current principal and interest payment is $3,000 per month, a refinance that lowers your interest rate by approximately 1% might reduce the payment by about $300 per month. A 2% rate reduction could reduce that $3k monthly PI by about $600!!
That's approximately:
- $300 per month
- $3,600 per year
- $18,000 over five years
But remember: this is only a shortcut for estimating potential savings. Mortgage payments are based on amortization, so the actual savings need to be calculated using your specific loan.
2. What About a 0.50% Rate Drop?
You don't necessarily have to wait for mortgage rates to drop a full percentage point.
A half-percent reduction can still be worth investigating.
The larger your mortgage balance, the more significant even a relatively small rate reduction can become.
For example, saving $150 per month equals:
$1,800 per year
Over five years, that's $9,000 in reduced monthly payments.
The question isn't simply, “Did rates drop 1%?”
The better question is:
“How much will I save compared with what the refinance will cost me?”
3. Your Loan Balance Makes a Big Difference
A rate reduction generally produces greater dollar savings on a larger mortgage.
Someone refinancing a $700,000 balance may have considerably more incentive to refinance after a modest rate reduction than someone with a $150,000 balance.
That's why generic advice such as “Never refinance unless rates drop at least 1%” can be misleading.
You need to run the numbers.
4. Don't Forget About the Loan Term
This is extremely important.
Suppose you've already made several years of payments on a 30-year mortgage and refinance into a brand-new 30-year loan.
Your monthly payment could drop partly because you're lowering the interest rate and partly because you're stretching the remaining balance over a longer repayment period.
That can improve monthly cash flow, but it doesn't automatically mean you're saving more money over the life of the loan.
You may be able to refi to a new term that matches how much time you have left on the current mortgage. For example if you have 25 years left on a 30 year loan, a refi may be available with a new term of just 25 years.
When comparing refinance options, look at:
Your new rate + new payment + closing costs + loan term.
5. Calculate Your Break-Even Point
A lower payment sounds great, but refinancing usually comes with costs.
One simple way to evaluate the transaction is to calculate the break-even period.
For example:
- Refinance one time costs: $4,000
- Monthly savings: $250
- $4,000 ÷ $250 = 16 months to breakeven
In this simplified example, it takes approximately 16 months of payment savings to recover the $4,000 refinance cost.
If you expect to keep the mortgage substantially longer than that, the refinance may deserve serious consideration.
6. Don't Refinance Based on Rate Alone
The lowest advertised mortgage rate isn't automatically the best deal.
One lender might quote a lower rate but charge thousands of dollars more in points and lender fees to get it.
Another lender could offer a slightly higher rate with dramatically lower costs.
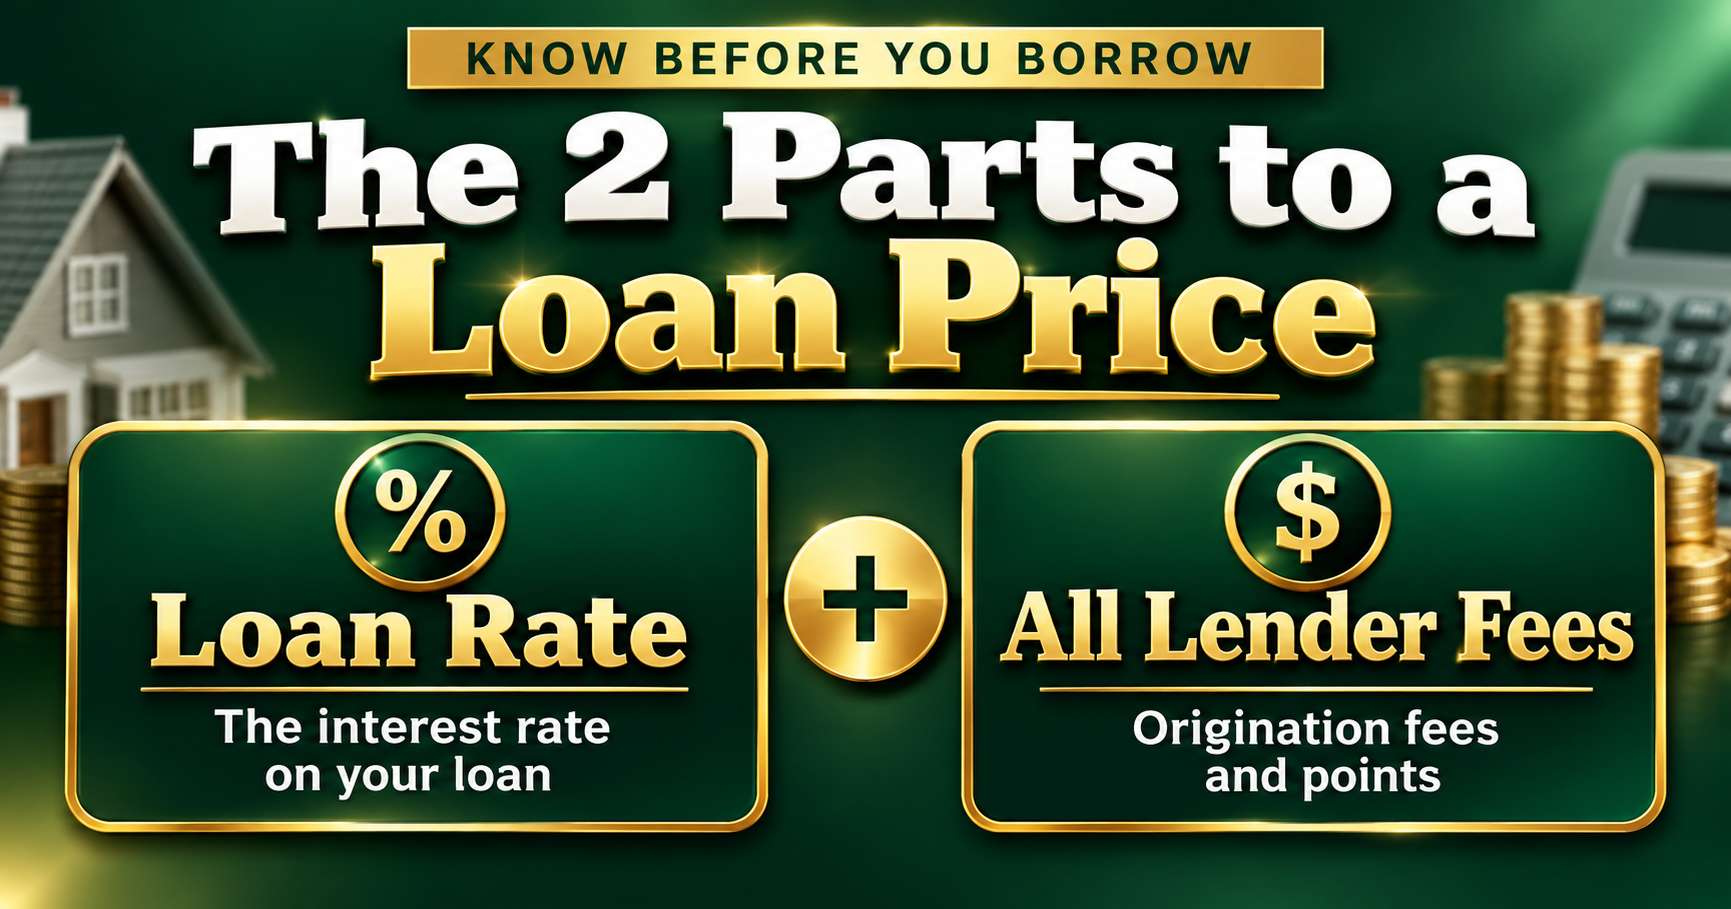
That's why I always recommend comparing the loan price, not just the rate.
Ask:
What rate am I getting, and what does it cost me to get that rate?
That's the number that matters.
7. Let Me Run the Numbers Before You Decide
If mortgage rates have dropped since you purchased or last refinanced your home, don't guess whether refinancing makes sense.
Let me run the numbers.
I'll compare your existing mortgage with today's refinance options and show you:
- Your estimated new principal and interest payment
- Your estimated monthly savings
- The cost of obtaining the new loan
- Your estimated break-even point
- Different rate and cost options
- Whether refinancing appears to provide a meaningful financial benefit
No sales pressure. Just the numbers so you can make an informed decision.
Bottom Line
A useful refinance rule of thumb is:
Every 1% reduction in your mortgage rate can reduce your monthly principal and interest payment by roughly 10%.
But that's only the starting point.
Don't refinance just because the rate is lower. Refinance when the numbers make sense.
Before accepting an offer from a bank, online lender, or mortgage company, get a second opinion and compare the complete loan price.
Shop the loan price, not just the rate!
Payment savings vary based on loan amount, interest rate, remaining loan term, new loan term, closing costs, points, and other factors. Examples are for illustration only and are not a loan offer or guarantee of savings.
- #refinance
More Refinancing Tips guides
Disclaimer: Informative opinion based on decades of experience, not legal advice. Guidelines change and lenders differ in their interpretation and overlays — verify details with the lender handling your loan.