Learning center
Refinancing Tips
When a refinance pays off, and how to run your own break-even math.
Overview
A refinance is worth doing when the savings recover the cost within a period you'll actually stay in the loan — and when you aren't quietly restarting a 30-year clock for a small monthly win. These guides cover rate-and-term versus cash-out, removing mortgage insurance, shortening the term, and the break-even arithmetic you can run yourself in a couple of minutes.
Who this is for: Current homeowners considering a refinance or cash-out.
What you'll learn
- •Break-even: total cost divided by real monthly savings
- •Rate-and-term versus cash-out pricing and appraisal requirements
- •Dropping mortgage insurance as your equity grows
- •Why resetting to a new 30-year term can cost more than it saves
10 guides in this topic
 Agent Loan Tips
Lenders, mortgage brokers and loan officers, what's the difference?
Who you choose for your home loan matters -- lenders, mortgage brokers and even loan officers are not the same
Read the guide → First Time Buyer
What Documents Are Needed For a Mortgage
Requirements by Loan Type. The paperwork required depends on your loan program, how you earn your income, and your financial situation. Conventional, FHA, VA, and USDA loans share many of the same requirements, but there are some important differences.
Read the guide → Monthly Payment Tips
Impound account tips
Depending on where you live and who you’re talking to, you may also hear these accounts called escrow accounts, impounds or trust accounts. Different names, but essentially the same concept: part of your monthly mortgage payment is set aside so your mortgage servicer can pay certain property-related bills when they come due.
Read the guide → Rate Tips
Shop the Loan Price, Not the Rate — What Does That Mean?
After my nearly 40 years in lending, there is one constant I can attest to. The bigger the lender the higher their loan price! What exactly is the loan price? It's the combination of the rate and lender fee tied to that rate
Read the guide → Property Condition & Appraisal
When an appraisal isn't needed
Fannie Mae’s appraisal waiver program—officially called Value Acceptance—can allow certain homebuyers and homeowners to complete a mortgage without a traditional appraisal.
Read the guide → Refinancing Tips
How fast can I refi my home loan?
How fast can I Refinance My Home? You may be able to refinance your home after just one year — and with some loan programs, even sooner. Whether you're looking to lower your interest rate, reduce your monthly payment, eliminate mortgage insurance, or take cash out of your home's equity, the key is knowing the refinance rules for your particular loan program.
Read the guide →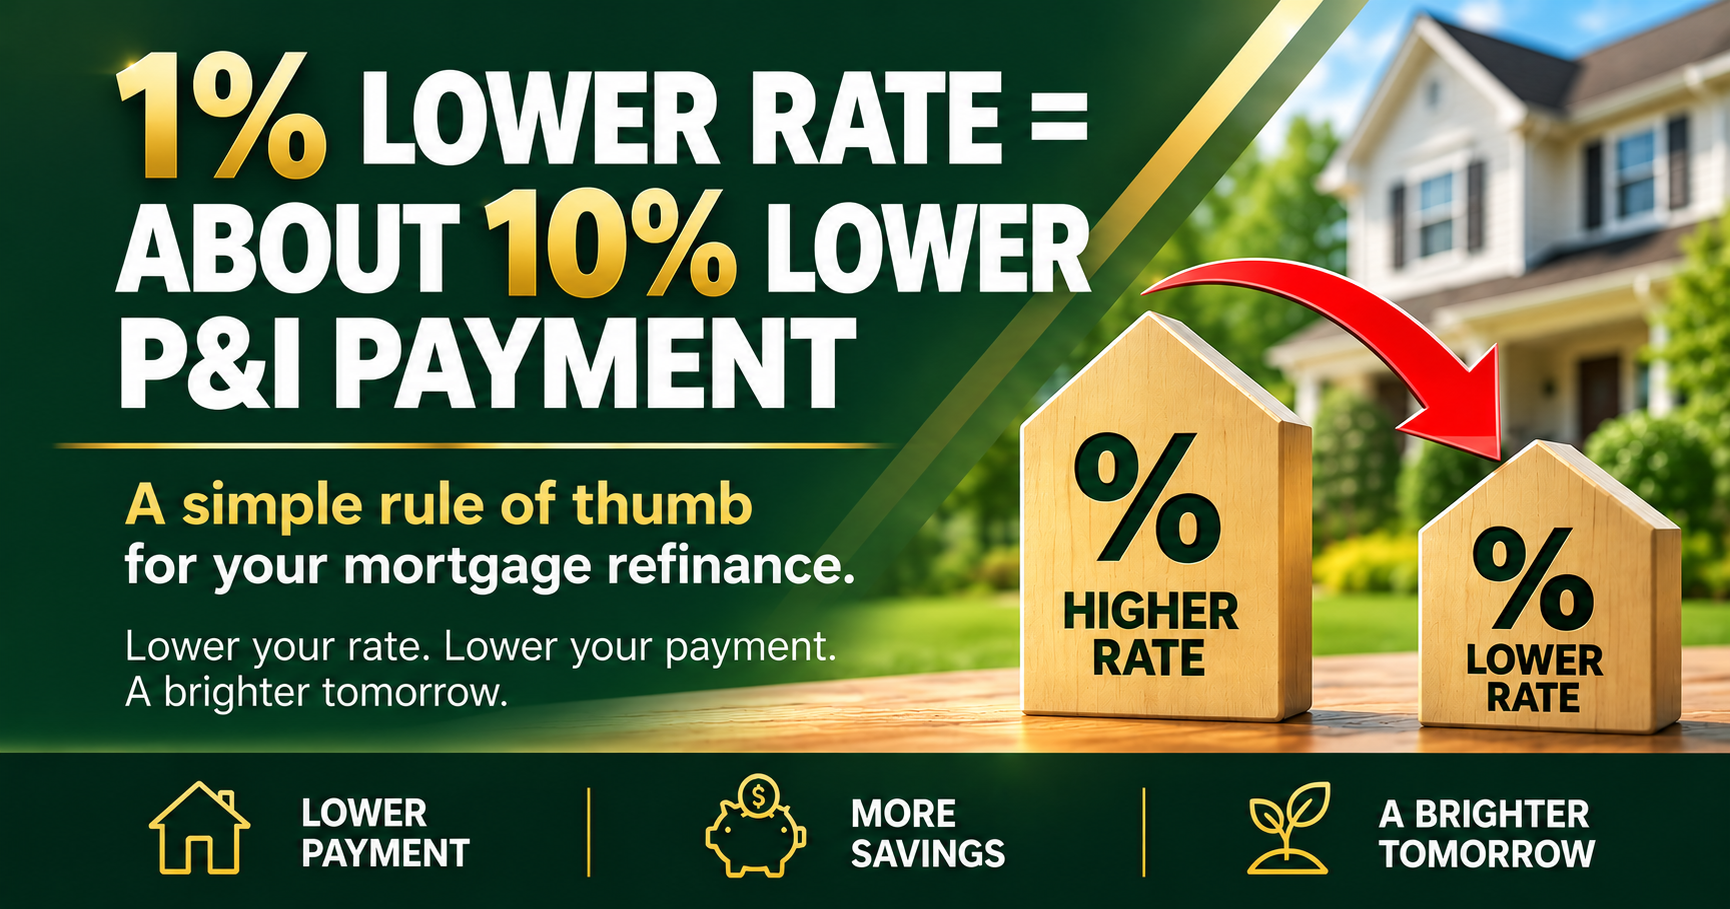 Refinancing Tips
A 1% Rate Drop Can Cut Your Principal & Interest Payment About 10%
Mortgage Refinance Rule of Thumb: A 1% Rate Drop Can Cut Your Principal & Interest Payment About 10%. When mortgage rates fall, homeowners often ask the same question: “How much lower does my rate need to go before refinancing makes sense?” There is no single answer that works for everyone, but there is a simple rule of thumb that can help you quickly estimate the potential savings:
Read the guide → Refinancing Tips
When Does a Refi to a Higher Rate Make Sense?
If you have a 3% mortgage rate, refinancing into a 6% mortgage probably sounds crazy. Why would anyone voluntarily give up a 3% mortgage? In most situations, you wouldn't. But there is one situation where refinancing to a higher mortgage rate can potentially make financial sense: you have substantial home equity AND you're buried in high-interest consumer debt.
Read the guide → Refinancing Tips
Refinance — Is It Worth It?
Refi tip----for every one percent in reduction from your current rate it will reduce your current principal and interest (PI) portion of your monthly payment by about 10%, a 2% reduction will reduce your PI payment by about 20%
Read the guide → Refinancing Tips
Track your home value for free
Your home may be your biggest financial asset. But if you don't know what it's worth today—or how much equity you've built—you could be overlooking valuable financial opportunities.
Read the guide →Get a straight answer today
No credit pull to start, no sales pressure, and a real quote you can compare line by line against any bank or big lender.